

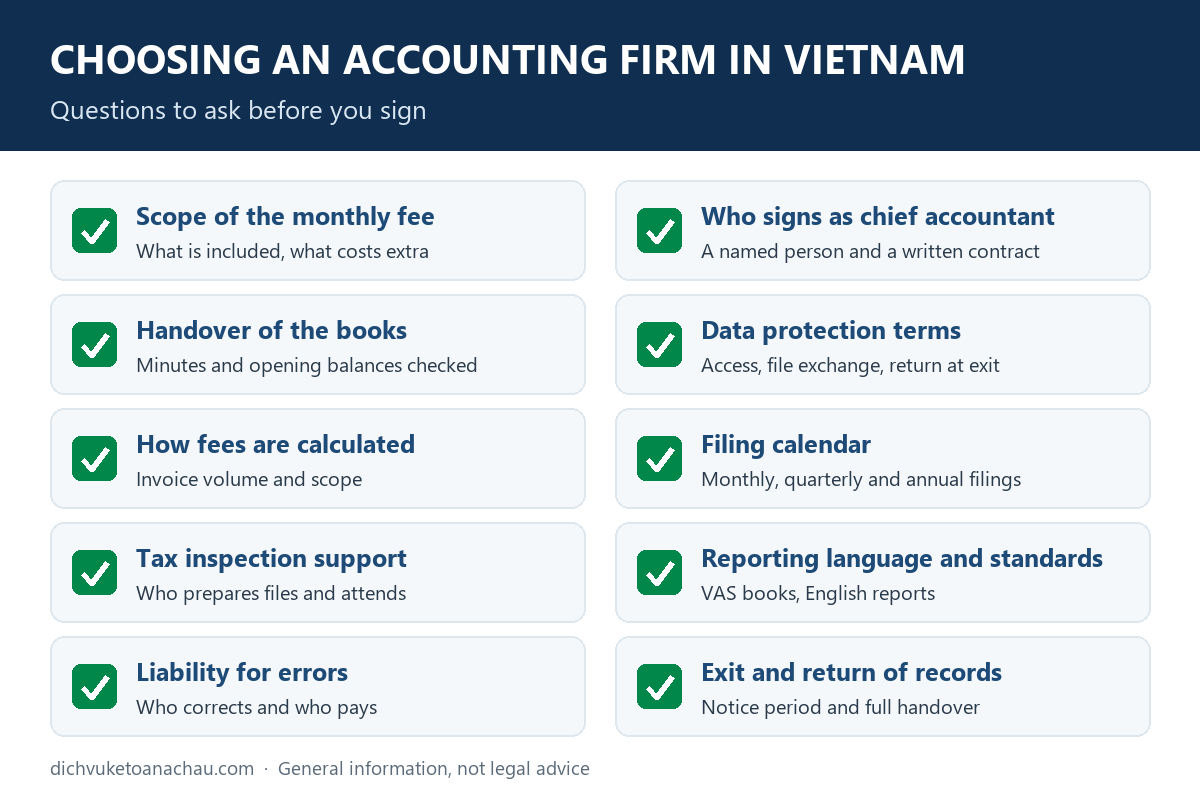
Choosing an accounting firm in Vietnam is less about the brochure and more about the answers you get to a short list of practical questions. Who signs as chief accountant? What does the monthly fee leave out? How will the books be taken over, and who pays if a filing goes wrong? Below are twelve questions, what a good answer sounds like, and the red flags.
Updated 15 October 2026. Written for directors and CFOs of foreign-invested companies appointing an outsourced accounting provider for the first time, or replacing the current one.
How to choose an accounting firm in Vietnam: the short answer
To choose an accounting firm in Vietnam, compare candidates on five things rather than on price alone. First, scope: a written list of what the monthly fee covers, from bookkeeping and tax returns to payroll, social insurance, year-end financial statements and reports for your parent company. Second, accountability: who will act as chief accountant, whether that person meets the standards in Article 54 of the Law on Accounting No. 88/2015/QH13, and the fact that your legal representative remains responsible for the choice. Third, continuity: how the firm takes over your books from the previous provider, and how it hands them back if you leave. Fourth, control: a filing calendar, data protection terms and support if the tax authority inspects. Fifth, the contract: a fee tied to invoice volume and scope, plus a clause on who pays for the firm’s own mistakes. A firm that answers all five in writing belongs on the shortlist.
Choosing an accounting firm in Vietnam: 12 questions at a glance
Use this table in the first meeting with each shortlisted firm.
| Question to ask | What a good answer looks like | Red flag |
|---|---|---|
| 1. What does the monthly fee cover? | A written scope, with extras priced separately | “Everything is included”, nothing in writing |
| 2. Who will be our chief accountant? | A named person meeting the Article 54 standards | No name until after signing |
| 3. Who is our contact, and in which language? | One named English-speaking contact, plus a back-up | A shared inbox that answers days later |
| 4. How will you take over our books? | Signed handover minutes and a check of opening balances | Starting “from this month” without looking back |
| 5. What is our filing calendar? | A written calendar with internal cut-off dates | “We will remind you” |
| 6. How is the fee calculated? | Tiers by invoice volume and scope, with written review triggers | A very low headline price, extras later |
| 7. How do you protect our data? | Named access and a data clause in the contract | Files sent through personal email or chat |
| 8. What if the tax authority inspects us? | File preparation and attendance, scope agreed in advance | “Not our job”, or a vague “we handle it” |
| 9. Which reports, language and standard? | VAS statutory reports plus English management reports | Tax returns only |
| 10. How do you work with our auditor? | Audit schedules ready and a named person for queries | Nobody assigned |
| 11. Who pays if you make a mistake? | Correction at the firm’s cost and an agreed liability limit | No liability clause |
| 12. How do we leave? | A notice period and full handover of records | Records held back during a fee dispute |
What does the monthly fee cover?
Scope is where most disappointments start: two quotes can look alike and cover very different work. Ask for the scope as a list attached to the contract, covering at least:
- Bookkeeping: invoices, bank transactions and payroll entries, with bank and VAT reconciliations.
- Tax filing: VAT, personal income tax withheld from salaries, foreign contractor tax where it applies, and corporate income tax.
- Payroll and social insurance: payslips, monthly contributions and declarations.
- Year-end: financial statements, corporate income tax finalization and statutory audit support.
- Parent-company reporting: management accounts in English, in your group’s format.
Then ask what is excluded: tax inspection support, transfer pricing documentation and clean-up of earlier years are common add-ons. Our accounting outsourcing services in Vietnam page sets out a full scope, and the guide to payroll and social insurance in Vietnam covers one of the heavier monthly items. Still deciding whether to outsource at all? Start with what an accounting services company in Vietnam does.
Who signs as chief accountant, and who stays accountable?
Every enterprise other than a micro enterprise must have a chief accountant. Article 50 of the Law on Accounting makes the legal representative responsible for appointing one or hiring a chief accountant service, which Article 56 allows under a written contract with an accounting service business. The person assigned must meet the Article 54 standards: integrity, an accounting qualification, a chief accountant training certificate and practical experience (detail in Decree 174/2016/ND-CP, Articles 20 to 22).
Ask for the name of the person who will sign, and to see the certificate and proof of experience. Resolution 66.18/2026/NQ-CP suspends the practising-registration and business-certificate rules for accounting services (Law on Accounting Articles 58 and 60) from 1 July 2026 to 28 February 2027, so for now the person and the contract are the better test. Our guide to the chief accountant requirement in Vietnam covers the criteria, and our accounting staff outsourcing service provides the role.
Who pays when the firm makes a mistake?
Hiring a firm does not move your legal responsibility. Under Article 56(3) of the Law on Accounting, your company must give the provider complete, timely and truthful information. Under Article 22(5) of Decree 174/2016/ND-CP, the legal representative stays responsible for hiring a chief accountant service. Toward the tax authority, the taxpayer is still your company.
The contract decides who bears the cost between you and the firm. Look for a clear split of tasks and deadlines, an obligation on the firm to correct its own errors at its cost, including late-payment interest or penalties caused by its delay, and a liability limit you can accept.
How will you take over our books from the previous provider?
Switching firms mid-year is manageable if the handover is run as a project. When a chief accountant changes, Article 20(4) of Decree 174/2016/ND-CP requires a handover of work and records and notice of the new name and specimen signature to your banks; the outgoing person stays responsible for their period. A good new firm builds on that:
- Handover minutes listing ledgers, filed returns, contracts, payroll files and e-invoice access.
- Opening balances checked against bank statements, tax filings and the last audited financial statements.
- An issues list with proposed fixes before the first month is closed.
- Access in your company’s name: bank and tax-portal credentials held by the company, not the firm.
If the opening check turns up gaps, a separate bookkeeping review is usually cheaper than fixing them month by month.
And when you leave
The contract should set a notice period and oblige the firm to return all records, working files and credentials at exit, whatever the state of any fee discussion. Accounting records belong to your company, which must keep them under the Law on Accounting.
How is our financial and payroll data protected?
Data handling is easy to overlook when choosing an accounting firm in Vietnam, yet the firm sees bank statements, margins and every employee’s salary, identity details and bank account. Vietnam’s personal data protection rules separate the company that controls personal data from a provider that processes it on the company’s behalf under a contract. The data terms therefore belong in the engagement contract. Ask:
- Who in the firm can open your files, and how access is removed when staff leave.
- Whether documents move through a folder or portal your company controls, rather than personal email or chat.
- Whether any work is subcontracted, and to whom.
- Whether copies are returned or deleted when the engagement ends.
Filing calendar, tax inspections and the statutory audit
A written filing calendar
Ask for a calendar of every monthly, quarterly and annual filing your company has under current regulations: VAT and personal income tax, provisional corporate income tax, social insurance, annual financial statements and corporate income tax finalization. It should also show your internal cut-off for sending documents. The Law on Tax Administration No. 108/2025/QH15 has applied since 1 July 2026, a reminder to review the calendar every year.
Support when the tax authority inspects
A tax inspection tests the books harder than any audit. Ask who prepares the files, who explains entries to inspectors, whether the firm attends meetings, and how that work is charged. If support is excluded or vague, budget for outside help; our tax risk management advisory and tax consulting service cover this work. Clean filings also decide how smoothly a final tax clearance goes, as our guide to closing a company in Vietnam shows.
Working with the statutory auditor
Foreign-invested enterprises have their annual financial statements audited by an independent audit firm under the Law on Independent Audit No. 67/2011/QH12 and its implementing rules. Your accounting firm should prepare the audit schedules, answer queries and post agreed adjustments. Our FDI audit readiness checklist lists what auditors usually request.
Which language and standards will our reports use?
Two sets of reports usually run side by side. The statutory books follow Vietnamese Accounting Standards (VAS) and the accounting regime that applies to your company, such as Circular 99/2025/TT-BTC for financial years beginning on or after 1 January 2026. If your parent reports under IFRS, ask who prepares the reconciliation.
Under Article 11(1) of the Law on Accounting, as amended by Law No. 56/2024/QH15 from 1 January 2025, Vietnamese is the written language of accounting. Financial statements that use a foreign language must show Vietnamese alongside it, and foreign-language documents must be translated when a competent authority asks. English management reports are agreed with the firm, so ask for a sample. Our guide to Vietnam Accounting Standards and bookkeeping explains where VAS and IFRS differ.
Service fees
Accounting packages start from VND 500,000/month. The quote depends on monthly invoice volume and scope: payroll headcount, bank accounts, foreign-currency transactions, parent reporting and audit support. Tiered pricing by invoice volume is fair to both sides if the contract says what happens when you change tier.
When choosing an accounting firm in Vietnam on price, be wary of a quote far below others for the same scope; the gap usually returns as extras or as work not done. Call 0776 112 333 or use the form below for a written quote.
Choosing or replacing your accounting firm in Vietnam?
Send a few details. An adviser contacts you to confirm the scope and sends a written quote.
Frequently asked questions
Should a foreign-invested company use a local or an international accounting firm?
Either can work. When choosing an accounting firm in Vietnam, what matters is statutory books kept under Vietnamese rules, a chief accountant who meets Article 54 of the Law on Accounting, and English reporting to your parent.
Can we switch accounting firms in the middle of the financial year?
Yes. Sign handover minutes, check opening balances, and notify your banks of the new chief accountant’s name and specimen signature, as Article 20(4) of Decree 174/2016/ND-CP requires. Avoid switching just before a major filing deadline.
Do our financial statements have to be in Vietnamese?
Vietnamese is the written language of accounting. Financial statements in a foreign language must also show Vietnamese, and foreign-language documents must be translated when a competent authority requests (Law on Accounting, Article 11(1), as amended by Law No. 56/2024/QH15).
Is our company still responsible if the accounting firm makes a mistake?
Toward the authorities, yes. Your company must supply complete, timely and truthful information (Law on Accounting, Article 56(3)), and the legal representative remains responsible for hiring a chief accountant service (Decree 174/2016/ND-CP, Article 22(5)). The contract decides who bears the cost of the firm’s errors.
How much does an outsourced accounting firm cost in Vietnam?
At Á Châu, accounting packages start from VND 500,000/month, depending on monthly invoice volume and agreed scope, quoted in writing after a short review of your records.
Related services: Accounting outsourcing in Vietnam · Chief accountant outsourcing · Tax consulting · Corporate tax finalization
Related guides: Chief accountant requirement in Vietnam · Bookkeeping review · All English guides · Vietnam tax and accounting FAQ
Achau Accounting · 343 Pham Ngu Lao, Ben Thanh Ward (former District 1), Ho Chi Minh City · +84 776 112 333 · linhcskh@dichvuketoanachau.com

