

The chief accountant requirement Vietnam places on companies is simple: every enterprise must appoint a chief accountant (kế toán trưởng) to head its accounting function unless it is a micro enterprise. The rule comes from the Law on Accounting No. 88/2015/QH13 and Decree 174/2016/ND-CP. A company that cannot appoint one straight away may name a person in charge of accounting for up to 12 months, or hire a chief accountant service.
Updated 28 September 2026. Written for directors and finance managers of foreign-invested companies: who must appoint, who qualifies, who is barred, what the role signs, and three ways to comply.
Does a company in Vietnam need a chief accountant?
Yes, in most cases. Article 50 of the Law on Accounting No. 88/2015/QH13 makes the legal representative responsible for appointing a chief accountant or deciding to hire a chief accountant service, and Article 20 of Decree 174/2016/ND-CP states that every accounting unit must appoint one, with narrow exceptions. For an enterprise, the standing exception is a micro enterprise under the SME support law, which may assign a person in charge of accounting instead. A limited liability company or joint stock company with foreign capital, including a 100% foreign-owned subsidiary, is therefore expected to have a chief accountant from the start of operations. If no suitable person is available yet, the company can assign a person in charge of accounting for a maximum of 12 months, or contract an accounting service business to provide a chief accountant. Whoever fills the role must meet the standards in Article 54 of the Law, and the legal representative remains accountable for the choice. A representative office of a foreign company sits outside this rule, because its head decides how accounting staff are arranged.
Which entities must appoint a chief accountant
The obligation attaches to the accounting unit, the legal entity that keeps its own books. Here is how the chief accountant requirement in Vietnam applies to the structures foreign investors use most:
| Entity type | Chief accountant required? | Legal basis |
|---|---|---|
| LLC or joint stock company, including 100% foreign-owned companies and joint ventures | Yes | Law Art. 50(2); Decree 174 Art. 20(1) |
| Micro enterprise under the SME support law | Not mandatory; may assign a person in charge of accounting | Decree 174 Art. 20(2)(b) |
| Branch of a foreign enterprise operating in Vietnam | Yes, with a university-level accounting qualification | Decree 174 Art. 20(1), 21(2)(l) |
| Representative office of a foreign enterprise | No; the head of office decides accounting staffing | Decree 174 Art. 23(1) |
| Company still recruiting | Person in charge of accounting (maximum 12 months) or a hired chief accountant service | Decree 174 Art. 20(1) |
Micro-enterprise status is set under the Law on Support for Small and Medium-sized Enterprises No. 04/2017/QH14 and its implementing decree, using headcount and revenue or capital thresholds that vary by sector. Status can change from year to year, so re-check it at each year-end. For the other start-up obligations, see our guide to company setup and business licensing for foreign investors.
Who qualifies: the criteria in Article 54 and Decree 174
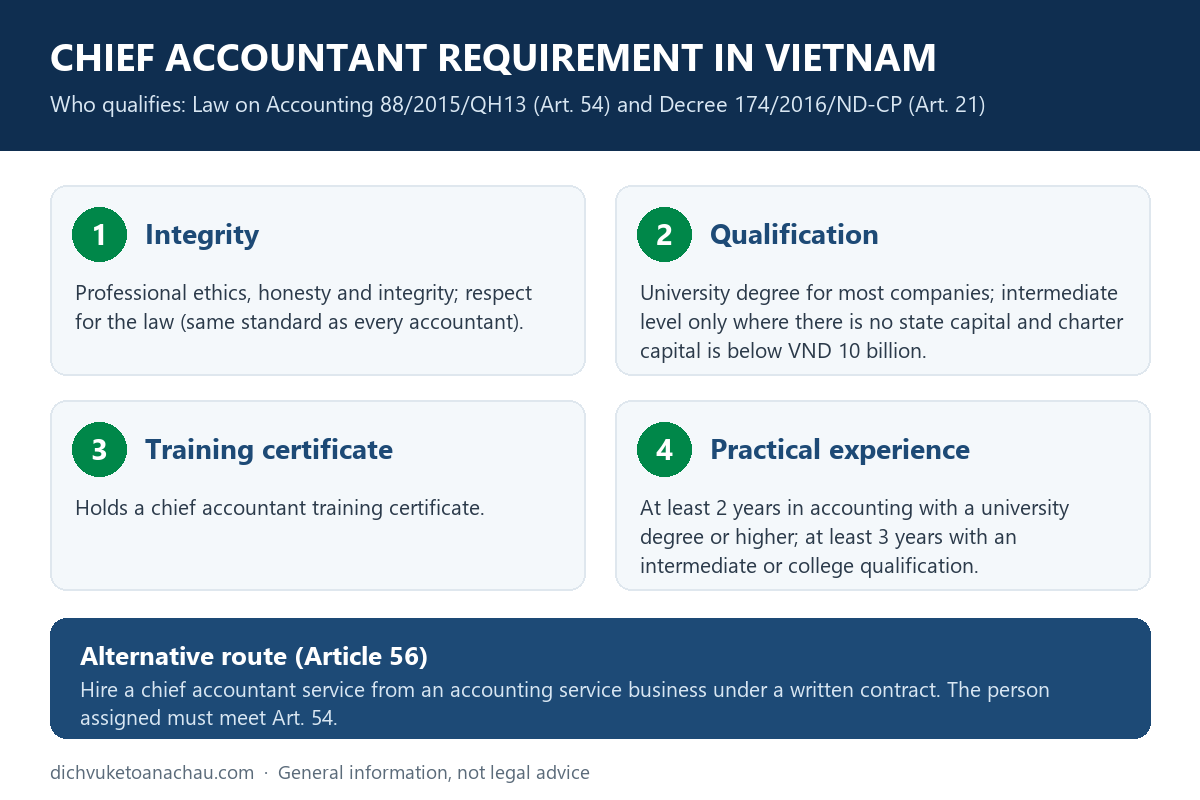
Article 54 of the Law on Accounting sets four standards, and Article 21 of Decree 174/2016/ND-CP adds the education level for each type of accounting unit. A candidate must meet all of them.
| Criterion | What is required | Source |
|---|---|---|
| Integrity | Professional ethics, honesty and respect for the law | Law Art. 51(1), 54(1)(a) |
| Qualification | University degree in accounting for enterprises generally and for foreign branches; intermediate level is enough where there is no state capital and charter capital is below VND 10 billion | Law Art. 54(1)(b); Decree 174 Art. 21(2)(i), (l), 21(3)(g) |
| Training certificate | Chief accountant training certificate issued under Ministry of Finance rules | Law Art. 54(1)(c); Decree 174 Art. 21(1) |
| Experience | At least 2 years of practical accounting work with a university degree; at least 3 years with an intermediate or college qualification | Law Art. 54(1)(d) |
| Parent companies with state capital | At least 5 years of practical accounting work for the chief accountant or person in charge of accounting of the parent company itself, where the parent is a state-owned enterprise or the State holds over 50% of its charter capital | Decree 174 Art. 21(5) |
| Not disqualified | Outside every group barred from accounting work | Law Art. 52; Decree 174 Art. 19 |
Nationality is not among the Article 54 criteria. A foreign finance manager can take the role only with the certificate and experience above, and should be able to work in Vietnamese. Under Article 11(1) of the Law, as amended by Law No. 56/2024/QH15 with effect from 1 January 2025, Vietnamese is the written language of accounting; financial statements that use a foreign language must show Vietnamese alongside it, and accounting documents in a foreign language must be translated into Vietnamese when a competent authority requests. Ask candidates for the certificate and proof of experience; our note on mistakes to avoid when hiring accountants covers the rest of the screening.
Who cannot be a chief accountant
Article 52 of the Law and Article 19 of Decree 174/2016/ND-CP bar these people from accounting work, and therefore from the chief accountant role:
- Legal capacity: minors, people whose civil act capacity a court has restricted or removed, and people under compulsory education or rehabilitation measures.
- Court and criminal matters: people banned from accounting by a court, under criminal prosecution, serving a prison sentence, or convicted of economic-management or finance-related office offences without the conviction expunged.
- Close relatives of management: parents, spouse, children and siblings (including adoptive relations) of the legal representative, the director or general director, the deputy in charge of finance, or the chief accountant of the same unit.
- Conflicting roles: managers or executives, warehouse keepers, cashiers, and people regularly assigned to buy and sell assets in the same unit.
The last two groups do not apply to a sole proprietorship, a single-member LLC owned by an individual, or a micro enterprise with no state capital. For a foreign-invested company owned by a corporate parent, that exception rarely helps: the general director cannot double as chief accountant, nor can the cashier or the director’s spouse.
What a chief accountant signs and answers for
Article 53 defines the chief accountant as the head of the accounting apparatus. Article 55 sets three core duties: complying with accounting and finance law, running the accounting function, and preparing financial statements under the accounting regime and standards, with professional independence. For enterprises that applied Circular 200/2014/TT-BTC, the regime for financial years beginning on or after 1 January 2026 is Circular 99/2025/TT-BTC, which replaced it, so the chief accountant owns the transition. Our guide to Vietnam Accounting Standards and bookkeeping covers the VAS side.
- Financial statements are signed by the preparer, the chief accountant and the legal representative (Law Art. 29(2)(d)).
- Accounting books carry the same three signatures (Law Art. 24(2)).
- Payment vouchers need the approver’s signature and the chief accountant’s, or an authorised person’s, before payment (Law Art. 19(3)).
When the chief accountant changes, Article 20(4) of Decree 174 requires a handover of work and records, and notice of the new name and specimen signature to the banks where the company holds accounts. The outgoing person stays responsible for their period. A clean handover matters most before a statutory audit, as our FDI audit readiness checklist explains.
Three ways to meet the chief accountant requirement Vietnam sets
| Option | Suits | Legal basis | Points to check |
|---|---|---|---|
| In-house chief accountant | Companies with a full accounting team and daily on-site review | Law Art. 53, 54; Decree 174 Art. 20, 21 | Certificate, degree, experience; no barred relationship or role; cover for leave and resignation |
| Hired chief accountant service | New subsidiaries, small local teams, companies between hires | Law Art. 56; Decree 174 Art. 22 | Written contract with an accounting service business; assigned person meets Law Art. 54 and Decree 174 Art. 21 |
| Person in charge of accounting | Micro enterprises; others for up to 12 months while recruiting | Law Art. 53(4); Decree 174 Art. 20 | Same standards and duties; track the 12-month limit |
The person-in-charge route is not a lighter standard: Article 53(4) requires that person to meet the chief accountant criteria and carry the same responsibilities. Only the title changes, plus a 12-month limit for companies that are not micro enterprises.
How a hired chief accountant service works
Article 56 of the Law allows a company to contract an accounting service business to provide a chief accountant, and Article 22 of Decree 174/2016/ND-CP adds the detail:
- Written contract setting out scope, responsibilities and fees (Law Art. 56(2)).
- Qualified person. The person the provider assigns must meet the standards in Article 54 of the Law (Law Art. 56(4)) and Article 21 of the Decree (Decree 174 Art. 22(3)). Resolution 66.18/2026/NQ-CP suspends the practising-registration and business-certificate rules for accounting services (Law on Accounting Articles 58 and 60) from 1 July 2026 to 28 February 2027.
- Same rights and duties as a chief accountant under Article 55, including signing financial statements (Decree 174 Art. 22(4)).
- Your obligations remain. The company must supply complete, timely and truthful information and documents and pay the agreed fees (Law Art. 56(3)), and the legal representative stays responsible for the decision to hire (Decree 174 Art. 22(5)).
How Á Châu can help
A typical scope covers monthly ledger review, accounting policies, review of tax returns before filing, signing the annual financial statements, and working with the auditor. Á Châu provides this through our accounting staff outsourcing service, standalone or combined with our accounting outsourcing services in Vietnam, which can also run the whole accounting function externally.
Common compliance mistakes to avoid
- Keeping an acting person in charge beyond 12 months in a company that is not a micro enterprise.
- Appointing the director’s spouse, sibling or child in a company owned by a corporate parent.
- Letting the general director or the cashier sign as chief accountant.
- Relying on a group finance manager abroad who lacks the training certificate.
- Changing chief accountant without handover minutes or bank notification.
These tend to surface in a tax inspection or audit, and administrative penalties apply under current regulations. If you are unsure whether your set-up meets the chief accountant requirement Vietnam imposes, start with a bookkeeping review; our tax consulting service can check the tax side at the same time.
About fees
Full-service accounting starts from VND 500,000/month. A chief accountant service is quoted after reviewing your company’s size and records, since transaction volume, bank accounts, payroll, related-party transactions and audit deadlines shape the scope. Call 0776 112 333 or use the form below.
Need a chief accountant for your company in Vietnam?
Four fields. An adviser contacts you to confirm the scope and sends a written quote.
Frequently asked questions
Can the general director also be the chief accountant?
Not in most foreign-invested companies. Managers and executives cannot do accounting work in their own unit. The exception covers only sole proprietorships, single-member LLCs owned by an individual, and micro enterprises with no state capital (Decree 174/2016/ND-CP, Article 19).
How long can a company operate without a chief accountant?
A person in charge of accounting can fill the gap for up to 12 months. After that, a company that is not a micro enterprise must have a chief accountant in place, either appointed or provided through a hired chief accountant service (Law on Accounting Article 50(2); Decree 174/2016/ND-CP Article 20).
Can a foreigner be the chief accountant of a Vietnamese company?
Nationality is not among the criteria in Article 54 of the Law on Accounting. The person must hold the training certificate and meet the qualification and experience rules. Vietnamese remains the written language of accounting: financial statements that use a foreign language must be bilingual, and foreign-language accounting documents must be translated into Vietnamese when a competent authority requests (Article 11(1), as amended by Law No. 56/2024/QH15).
Does a hired chief accountant carry the same role as an employee?
In accounting terms, yes. The person works under a written contract and must meet the same Article 54 standards (Law on Accounting, Article 56(2) and (4)), and holds the chief accountant’s rights and responsibilities under Article 55, including signing financial statements (Decree 174/2016/ND-CP, Article 22(4)).
Does a representative office need a chief accountant?
It is not mandatory. Under Article 23 of Decree 174/2016/ND-CP, the head of the representative office decides how accounting staff are arranged.
Related services: Chief accountant and accounting staff outsourcing · Corporate tax finalization · Accounting outsourcing
Achau Accounting · 343 Pham Ngu Lao, Ben Thanh Ward (former District 1), Ho Chi Minh City · +84 776 112 333 · linhcskh@dichvuketoanachau.com
More English guides: Accounting and tax guides for foreign companies in Vietnam · Questions foreign finance teams ask about Vietnamese tax and accounting

